
Corporate Credit and the Institutional Portfolio: Reasserting First Principles
Key Takeaways
- A first-principles approach to forming a corporate credit allocation begins with recognition that public and private debt markets offer a distinct form of compensation: the credit risk premium.
- The strategic allocation should be built from a diversified portfolio of public corporate bonds, which offer unmatched scale, breadth, and transparency. Syndicated loans and private credit can complement the public-market foundation but should not supplant it.
- A well-designed systematic credit strategy is a natural core for the public-credit exposure; discretionary active public bond strategies can provide additional sources of alpha.
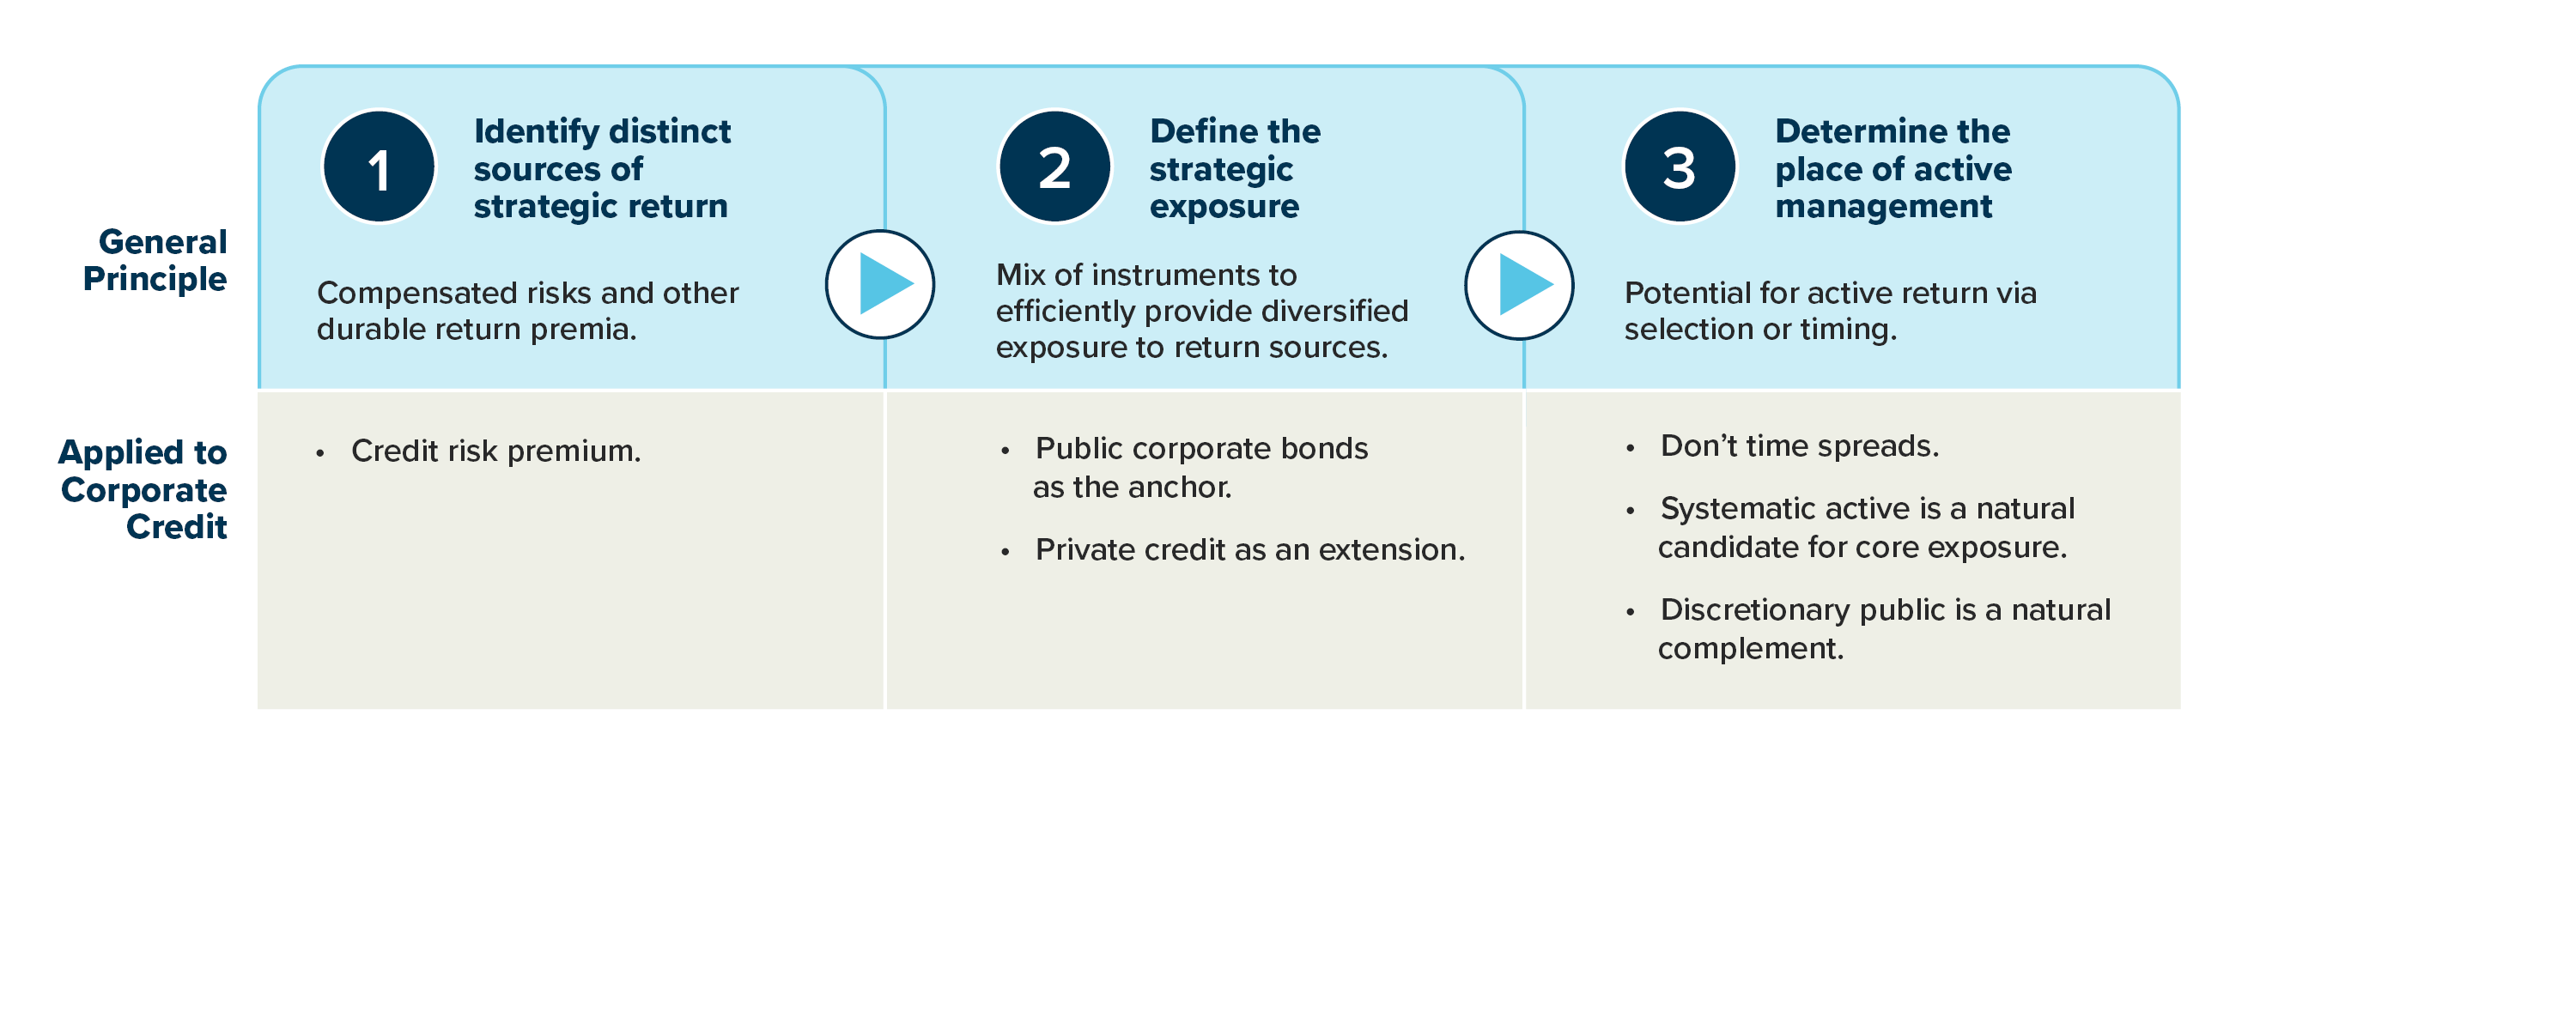
Construction of an allocation to any asset class should follow a logical sequence: (1) start with a clear understanding of the distinct and enduring return premia it offers; (2) determine the mix of instruments that best provides strategic exposure to those premia; and (3) decide whether and how to take active views.
In corporate credit, these steps are often blurred. Corporate credit merits a place in institutional portfolios because the market rewards investors for bearing credit risk, but investors often conflate the credit risk premium with other purported sources of return, most notably illiquidity. They also often skip ahead to active decisions such as the pursuit of private-market opportunities and tactical positioning based on spreads before determining how best to build strategic exposure to the credit risk premium.
In this note, we reconsider the construction of a corporate credit allocation in the proper order, as visualized in Figure 1. To begin, we restore the credit risk premium to its proper place as the basis of the allocation. Next, we establish why investment-grade and high-yield corporate bonds provide the natural foundation for strategic corporate credit exposure and why private credit can complement that foundation but cannot appropriately substitute for it.
Figure 1: A Logical Process to Construct an Asset Class Allocation—The Case of Corporate Credit
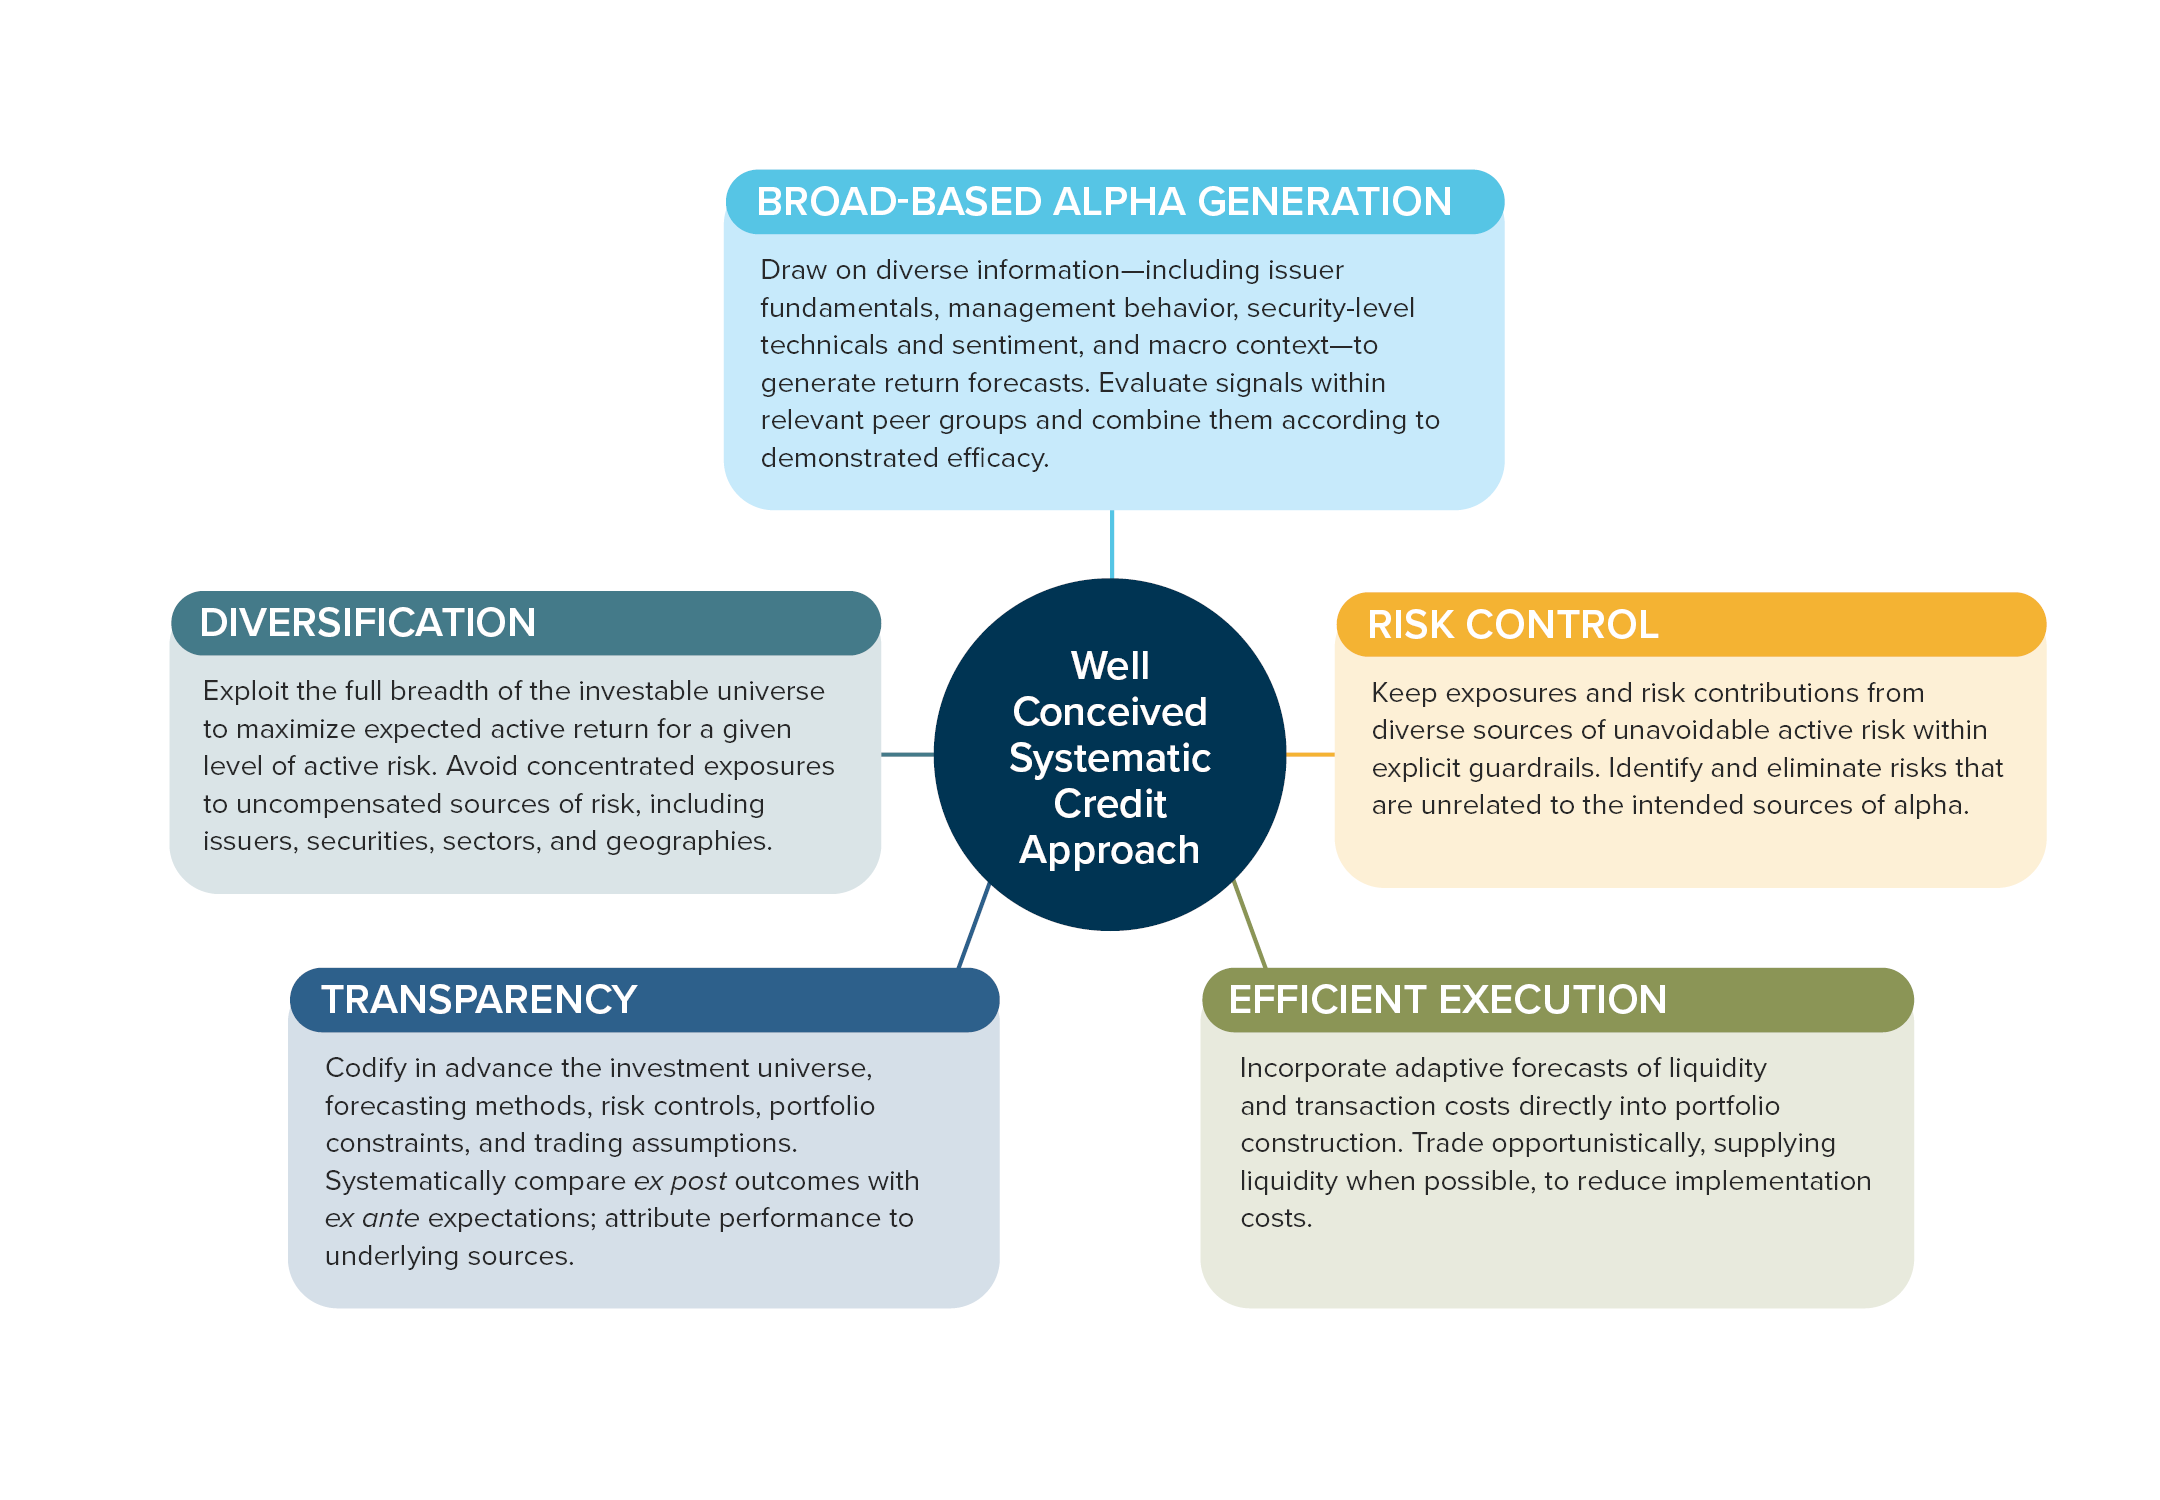
Finally, in determining the place of active management in corporate credit, we review the practical limits of passive implementation and the challenges of timing credit spreads. We then highlight five characteristics of a systematic active credit strategy that make it a natural candidate for the core of a corporate credit allocation— broad-based alpha generation, diversification, risk control, transparency, and efficient execution.
A Distinct Source of Strategic Return: The Credit Risk Premium
Corporate credit merits a place in institutional portfolios because investors earn a premium for bearing credit risk. Corporate borrowing is a critical feature of the global economy. Whether credit is extended by a bank or by investors in public or private debt, the provider of capital bears the risk that deterioration in the borrower’s fundamentals reduces the value of the claim or ultimately leads to default and loss. Allocation of that risk is a central function of global capital markets, and the compensation for bearing it is the credit risk premium.
The credit risk premium is conceptually distinct from other major risk premia, including the term premium, which compensates government bond investors for risks of holding longer- rather than shorter-term debt, and the equity premium, which compensates stockholders for bearing residual claims on corporate earnings and asset values.
Consistent with this economic logic, long-run empirical evidence shows that corporate credit is additive in diversified portfolios. In 2023 research, for example, we found that 1) the credit risk premium generated a Sharpe ratio comparable to those of the equity and term premia, 2) portfolios combining credit with government bonds or equities delivered higher risk-adjusted returns than each of those individual asset classes alone, and 3) an equal-weighted combination of all three performed better still.1
Defining Strategic Exposure: An Anchor in Corporate Bonds
The next logical step in the allocation process is to determine how best to obtain strategic exposure to the credit risk premium. Public corporate bonds provide the natural foundation for several reasons.
Public investment-grade and high-yield bonds constitute, by far, the largest institutional corporate-credit market. Their benchmark-eligible global universe totals roughly $17 trillion. By comparison, the broadly syndicated loan and private-credit markets each total approximately $2.0–$2.5 trillion.
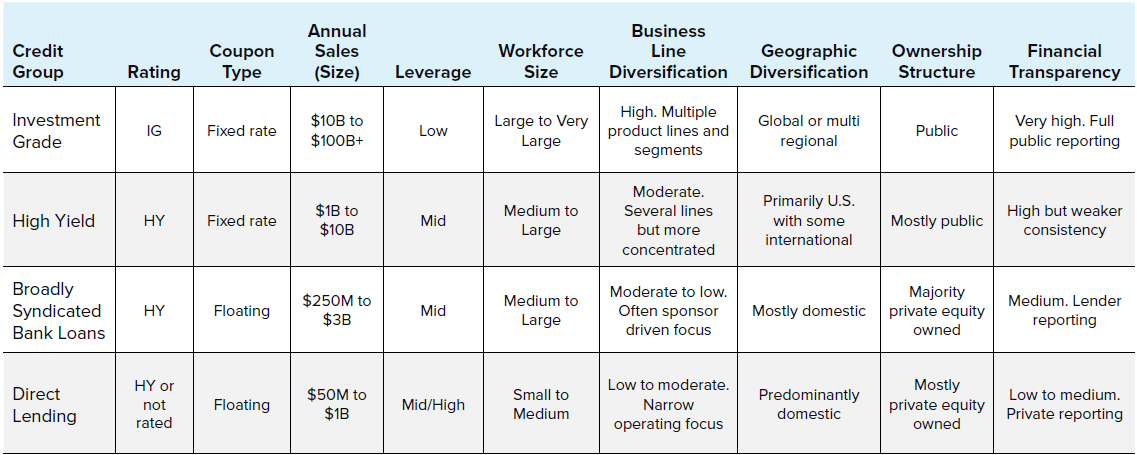
Beyond scale, Table 1 illustrates that publicly traded bonds offer an enormous diversification advantage. Syndicated loans and direct lending are concentrated largely in high-yield or unrated obligations of relatively small U.S.-based firms. Corporate bonds, by contrast, span a much larger universe of issuers across credit quality, industries, and geographies. That breadth matters because investors are not compensated for risks that can be diversified away; unnecessary concentration reduces expected risk-adjusted returns.
Table 1: Major Corporate Credit Markets—A Comparison of Typical Characteristics
Transparency is another comparative advantage of corporate bonds. A strategic allocation is easier to construct and monitor when composed of instruments that have relatively standardized terms, broadly available documentation, and observable market prices. Building a well-diversified portfolio from bespoke, opaque, and illiquid instruments, such as private loans, would be much more complicated and costly. A decision to take such a path should require strong evidence that doing so offers sufficient incremental compensation to offset those disadvantages.
What, then, is the strategic role of syndicated loans and private credit? They extend the opportunity set to borrowers, financing structures, and contractual terms that are not comprehensively represented in corporate bonds. They are, therefore, natural candidates to complement the public-market foundation. But while corporate bonds earn their place in the strategic allocation through scale, diversification, and transparency, the inclusion of syndicated loans and private credit—which do not share the same advantages—should be backed by evidence that they improve expected portfolio outcomes, not merely by the fact that they are different.
A longstanding argument in support of such inclusion has been that private credit offers an additional illiquidity premium. But Palhares and Richardson (2019) test for an illiquidity premium in public corporate bond markets and are “unable to find any empirical evidence.”2 While less-liquid bonds have somewhat wider spreads and directionally higher average returns, they also exhibit substantially greater volatility, leaving little improvement in risk-adjusted outcomes. That conclusion is robust across multiple measures of liquidity and different empirical approaches. This result calls into question the broader presumption that illiquidity commands a meaningful premium in credit markets.
A more recent argument is that banks’ retreat from corporate lending after the global financial crisis created a particularly attractive opportunity for private credit. But that argument, too, warrants scrutiny, because corporate bond markets have also participated in the broader shift toward non-bank financing.
In addition, private credit’s opacity complicates the assessment of its purported benefits. Differences in borrower and loan characteristics can legitimately affect expected returns. Higher fees, lower liquidity, and discretionary valuation practices, meanwhile, affect what investors ultimately earn and how much risk appears in reported performance. Such issues make it easy to mistake differences in measurement or implementation for differences in underlying economic compensation.
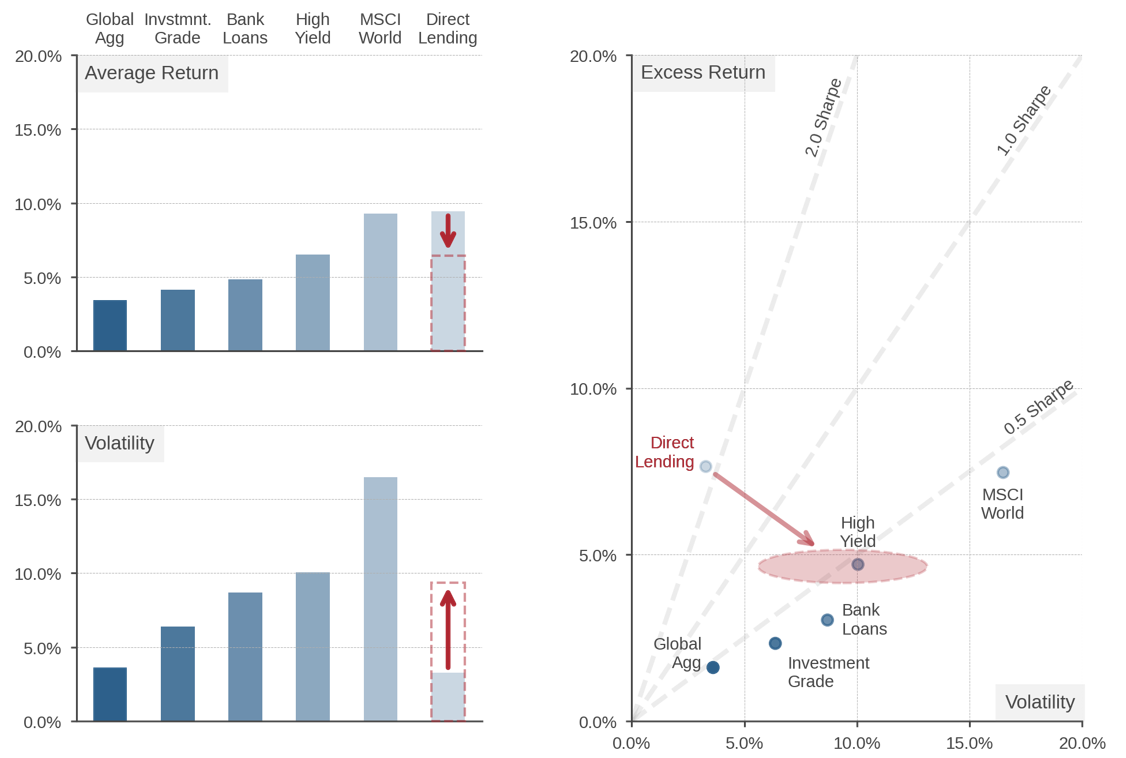
Using direct lending as an example, Figure 2 illustrates the importance of adjusting reported performance for fees and understated risk. Doing so (1) lowers reported returns by 3% to reflect an estimate of private-fund fees and expenses (top column chart) and (2) increases reported volatility to levels comparable with the average of syndicated bank loans and high-yield bonds (bottom column chart). The scatter chart shows that these changes result in a Sharpe ratio for direct lending that is broadly in line with public credit markets.3 The absence of superior risk-adjusted returns for private credit is reinforced by the performance of business development companies and private-company fixed-rate bonds that are included in standard corporate bond indices. There is nothing special about private credit.
Figure 2: Risk-Adjusted Performance of Direct Lending—Correcting for Distortions in Reported Results
The implication is clear. A diversified portfolio of publicly traded bonds should anchor the strategic corporate credit allocation. Syndicated loans and private credit can usefully broaden the allocation, but neither should be presumed to warrant coequal status with corporate bonds. This does not rule out the possibility that private credit offers attractive opportunities for alpha generation through security selection or other forms of manager value-add. But private investments justified on such grounds should be treated as active bets layered onto, rather than as substitutes for, diversified exposure to the credit risk premium via corporate bonds.
The Role of Active Management: Systematic as the Core
Once public credit is established as the anchor of the strategic corporate credit allocation, the next decision concerns the role of active management. We consider salient questions.
Should Investors Maintain Allocations to Corporate Credit Even When Spreads Are Tight?
Generally, yes. Corporate credit earns a strategic place in the portfolio because it offers exposure to the long-run credit risk premium. Like any other strategic allocation, corporate credit’s weight should change when an institution’s long-term objectives or its assessment of the asset class’s long-run risk and return prospects change, not simply because spreads appear tight or wide. Moreover, empirical evidence shows that tactical decisions to increase or decrease overall credit exposure are difficult, particularly when based primarily on current spread levels. In prior research, we evaluated more than 100,000 hypothetical timing strategies across multiple regions and sectors. Nearly 70% underperformed a simple buy-and-hold allocation, and apparent success was rarely robust across markets or specifications.4 The implication is that the credit risk premium is better owned than timed.
Does Active Management Have a Place in the Public Anchor?
Yes. In fact, to some degree by necessity. Active management has long been the default in public credit in part because truly passive implementation is difficult. Bonds have finite lives; issuers maintain multiple securities with different maturities, coupons, seniority, call features, and liquidity; and the investable universe changes continuously as debt is issued and retired. Decentralized trading and substantial variation in liquidity and transaction costs across bonds further complicate efficient benchmark replication. As a result, even ostensibly passive approaches require consequential decisions about portfolio construction, security selection, turnover, and execution.
How Should an Active Allocation Be Structured?
A well-designed systematic active corporate bond strategy—an approach that applies quantitative methods across a broad investment universe for return forecasting and portfolio construction—is a natural candidate to serve as the core of a public-credit allocation. As illustrated in Figure 3, such a strategy possesses five characteristics that support such a role: broad-based alpha generation, diversification, risk control, transparency, and efficient execution.
Figure 3: Five Characteristics of a Systematic Credit Strategy Appropriate for the Core
The idea of a systematic core may come as a surprise to many asset owners. Discretionary management has long dominated public credit, in part because limited transaction data, manual trading, and the difficulty of evaluating and efficiently trading large numbers of bonds historically hindered systematic investing. As we have discussed in prior research, however, those impediments have eased materially over the past decade with the electronification of corporate bond markets, improved market data, and advances in computing.5
This does not imply that a public corporate bond allocation should be purely systematic. In prior research, we have shown that leading discretionary managers often have limited exposure to the characteristics captured by a systematic credit approach.6 The finding suggests that discretionary management can play a valuable complementary role alongside systematic strategies, assuming appropriate risk management across the combined portfolio.
Conclusion
In asset allocation, the order in which decisions are made matters. In corporate credit, investors often skip what should be the first step—identifying the source of strategic return—and also allow active views to shape the strategic exposure rather than follow from it. The result can be unnecessary complexity, unrecognized risk, and costly exposures that do not improve expected investment outcomes.
Following the proper sequence means first acknowledging the credit risk premium as the source of strategic return and then building the strategic allocation around a diversified portfolio of public corporate bonds. Well-designed systematic active strategies are a natural core for that public-market exposure, potentially complemented by discretionary corporate bond strategies. Other credit exposures, including private credit and syndicated loans, can further broaden the allocation but should not substitute for a sound public-market foundation.
Endnotes
- See Acadian, Current Opportunities in Public Credit Markets, October 2023.
- Diogo Palhares and Scott A. Richardson, “(Il)liquidity Premium in Credit Markets: A Myth?,” The Journal of Fixed Income 28, no. 3 (Winter 2019): 5–23.
- See Acadian, The Private Party of the Corporate Credit Market, December 2023, where a version of the chart first appeared, for further discussion.
- See Acadian, Market Timing is Difficult—Credit is No Exception!, August 2025.
- See Acadian, Credit’s Systematic Shift, June 2026 and Acadian, The Rise of Systematic Credit … Again, March 2026.
- See Acadian, Current Opportunities in Public Credit Markets, October 2023.
Don't miss the next Acadian Insight
Get our latest thought leadership delivered to your inbox
Hypothetical Legal Disclaimer
The hypothetical examples provided in this presentation are provided as illustrative examples only. Hypothetical performance results have many inherent limitations, some of which are described below. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown. In fact, there are frequently sharp differences between hypothetical performance results and the actual performance results subsequently achieved by any particular trading program. One of the limitations of hypothetical performance results is that they are generally prepared with the benefit of hindsight. In addition, hypothetical trading does not involve financial risk, and no hypothetical trading record can completely account for the impact of financial risk in actual trading. For example, the ability to withstand losses or to adhere to a particular trading program in spite of trading losses are material points which can also adversely affect actual trading results. There are numerous other factors related to the markets in general or to the implementation of any specific trading program which cannot be fully accounted for in the preparation of hypothetical performance results and all of which can adversely affect actual trading results.
Legal Disclaimer
These materials provided herein may contain material, non-public information within the meaning of the United States Federal Securities Laws with respect to Acadian Asset Management LLC, Acadian Asset Management Inc. and/or their respective subsidiaries and affiliated entities. The recipient of these materials agrees that it will not use any confidential information that may be contained herein to execute or recommend transactions in securities. The recipient further acknowledges that it is aware that United States Federal and State securities laws prohibit any person or entity who has material, non-public information about a publicly-traded company from purchasing or selling securities of such company, or from communicating such information to any other person or entity under circumstances in which it is reasonably foreseeable that such person or entity is likely to sell or purchase such securities.
Acadian provides this material as a general overview of the firm, our processes and our investment capabilities. It has been provided for informational purposes only. It does not constitute or form part of any offer to issue or sell, or any solicitation of any offer to subscribe or to purchase, shares, units or other interests in investments that may be referred to herein and must not be construed as investment or financial product advice. Acadian has not considered any reader's financial situation, objective or needs in providing the relevant information.
The value of investments may fall as well as rise and you may not get back your original investment. Past performance is not necessarily a guide to future performance or returns. Acadian has taken all reasonable care to ensure that the information contained in this material is accurate at the time of its distribution, no representation or warranty, express or implied, is made as to the accuracy, reliability or completeness of such information.
This material contains privileged and confidential information and is intended only for the recipient/s. Any distribution, reproduction or other use of this presentation by recipients is strictly prohibited. If you are not the intended recipient and this presentation has been sent or passed on to you in error, please contact us immediately. Confidentiality and privilege are not lost by this presentation having been sent or passed on to you in error.
Acadian’s quantitative investment process is supported by extensive proprietary computer code. Acadian’s researchers, software developers, and IT teams follow a structured design, development, testing, change control, and review processes during the development of its systems and the implementation within our investment process. These controls and their effectiveness are subject to regular internal reviews, at least annual independent review by our SOC1 auditor. However, despite these extensive controls it is possible that errors may occur in coding and within the investment process, as is the case with any complex software or data-driven model, and no guarantee or warranty can be provided that any quantitative investment model is completely free of errors. Any such errors could have a negative impact on investment results. We have in place control systems and processes which are intended to identify in a timely manner any such errors which would have a material impact on the investment process.
Acadian Asset Management LLC has wholly owned affiliates located in London, Singapore, and Sydney. Pursuant to the terms of service level agreements with each affiliate, employees of Acadian Asset Management LLC may provide certain services on behalf of each affiliate and employees of each affiliate may provide certain administrative services, including marketing and client service, on behalf of Acadian Asset Management LLC.
Acadian Asset Management LLC is registered as an investment adviser with the U.S. Securities and Exchange Commission. Registration of an investment adviser does not imply any level of skill or training.
Acadian Asset Management (Singapore) Pte Ltd, (Registration Number: 199902125D) is licensed by the Monetary Authority of Singapore. It is also registered as an investment adviser with the U.S. Securities and Exchange Commission.
Acadian Asset Management (Australia) Limited (ABN 41 114 200 127) is the holder of Australian financial services license number 291872 ("AFSL"). It is also registered as an investment adviser with the U.S. Securities and Exchange Commission. Under the terms of its AFSL, Acadian Asset Management (Australia) Limited is limited to providing the financial services under its license to wholesale clients only. This marketing material is not to be provided to retail clients.
Acadian Asset Management (UK) Limited is authorized and regulated by the Financial Conduct Authority ('the FCA') and is a limited liability company incorporated in England and Wales with company number 05644066. Acadian Asset Management (UK) Limited will only make this material available to Professional Clients and Eligible Counterparties as defined by the FCA under the Markets in Financial Instruments Directive, or to Qualified Investors in Switzerland as defined in the Collective Investment Schemes Act, as applicable.