Concentrated equity investing—allocating to discretionary strategies that hold a very small number of stocks—gained prominence more than a decade ago in response to performance pressures facing asset owners after the global financial crisis. While concentration was an intuitive response to a real problem, it also appeals to some of investors’ most self-destructive behavioral vulnerabilities.
In this discussion, we show how three of these vulnerabilities help to explain concentrated equity’s rise in popularity, and we bring to light underappreciated risks. But first, we set the stage by contrasting concentration in its ideal form to the reality of how it is often put into practice.
Concentration: Ideal and Reality
Concentrated equity was a response to asset owners’ search for higher returns in a post-financial-crisis environment of low interest rates and skepticism that equity beta would suffice to meet ambitious performance targets. A rationale for concentration arose from scrutiny of equity managers’ stock picking prowess and what they were charging for it.
Academic literature from the late 2000s captured frustration with fees. It accused diversified discretionary managers of “closet indexing,” charging active fees for quasi-passive product by bloating their portfolios with stocks about which they knew little simply to absorb AUM.1 A skill-based motivation arose out of the “best ideas” literature, academic research that found discretionary mutual fund managers’ largest active positions were also their strongest performers.2 It didn’t seem much of an extrapolation from those results to suggest that focusing stock pickers on producing just a few “high conviction” ideas might improve net-of-fee results delivered to asset owners.3
Crucially, the foregoing motivations for investing in concentrated strategies does not imply that asset owners should hold an undiversified equity portfolio. They do not imply a rejection of diversification, just a shift in the locus of diversification from the investment manager(s) to the asset owner. The asset owner could select and construct a well-diversified collection of concentrated managers.
| In Homer’s Odyssey, the Sirens drove sailors to their deaths by enchanting them with their songs. Concentrated equity bears a resemblance, in that it is alluring yet dangerous. | 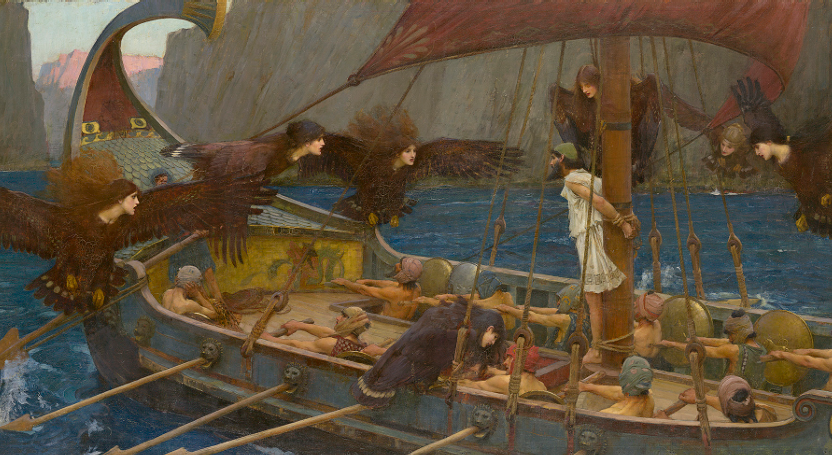
John William Waterhouse, Ulysses and the Sirens, 1891. National Gallery of Victoria, Melbourne. Purchased, 1891. Image courtesy National Gallery of Victoria, Melbourne |
In assessing how well the concept of concentration translates into the real world, we would pose three questions:
Do concentrated managers actually deliver superior stock picking skill? Unfortunately, our empirical analysis does not suggest that they do, as a group. In a broad study of U.S. long-only institutional equity strategies from 2013-2023, we found no evidence that concentrated managers delivered higher alpha.4 To be clear, the results do not imply that concentrated managers with exceptional stock picking ability don’t exist. But they do suggest that asset owners should expect that they will have to work to find them, which begs a follow-on question …
Does implementing a concentrated allocation pose special challenges? Yes. In fact, concentration increases the difficulty of manager selection. That’s because all else equal, holding fewer stocks produces a return stream with higher active risk than a well-diversified portfolio. More noise means it will take more data (a longer track record), to confirm the signal, i.e., to conclude that the concentrated manager has alpha with any given degree of statistical confidence.
In addition, our empirical work showed how concentration presents challenges for risk control and performance analysis. Concentrated portfolios exhibit greater style drift, greater variation in risk exposures, and suboptimal tradeoffs between drivers of outperformance, like value and momentum. In addition to noisier returns, these characteristics likely reflect reliance on heuristic methods in portfolio construction.5
Will asset owners actually implement a concentrated allocation in its ideal form? Unfortunately, in our experience, the answer is no. Many investors who go down the path of concentration do not implement well-diversified allocations. Many hold narrow and biased collections of concentrated strategies, perhaps even a single manager or a few growthy ones. The allure of concentration and the tendency to underdiversify in its execution are hardly surprising, because both are tied to deeply rooted behavioral biases.
Preference for Right Skewness
One of these biases is a preference for right skewness. For thousands of years, people have been drawn to lotteries, games that offer the possibility of a large payoff, but where the chance of winning is small and paying to play is a losing proposition in the long term. This bias is pervasive in investing, too. Academic research has documented investors’ willingness to pay up for assets whose return distributions have a “fat right tail.”6 The tendency helps to explain important patterns in asset pricing, including the low-volatility mispricing and the value premium.
There is a direct connection between the preference for right skewness and the allure of concentration. For a mean-variance investor, diversification is definitively a good thing in concept, because holding more stocks reduces risk (all else equal). But that is not the case for an investor who wants a shot at an outsized payoff: diversification quickly tamps down the right tail of the return distribution. As a result, investors who prefer skewness might opt to hold just a few stocks,7 and perhaps stocks with a biased set of characteristics, e.g., load up on speculative growth.8
But concentration may materially increase the risk of significant portfolio underperformance over the long-term. Empirically, more stocks have performed poorly than well in the long run, and a small number of stocks have accounted for a large portion of market gains.9 Holding fewer stocks may significantly increase the risk of missing out on the few exceptional winners, which increases the probability that any chosen concentrated portfolio will underperform.10
This concern is especially relevant in a world where many benchmarks have become highly concentrated, driven by stellar returns of stocks like the Magnificent 7 in the U.S. and TSMC in emerging markets.11,12 Their conspicuous performance has helped to normalize the idea of holding just a few stocks, and growthy ones at that. Ironically, however, the appropriate lesson is to diversify, because predicting in advance which few stocks will deliver stellar returns is an enormous challenge. You may get the theme right in many respects yet still miss out on upside.13
Disproportionate Focus on “Winners”
A second bias that helps to explain concentration’s allure and that influences its implementation is a disproportionate focus on “winners.” The financial media, for example, lavishes attention on managers that have generated exceptional outperformance—until they don’t. Famous examples of lionized managers whose stars quickly fell include Bruce Berkowitz and Bill Miller. But fawning manager profiles and lists of rising stars, the 30 under 30, best performing funds, and so on, make for enduringly effective clickbait.
Concentrated strategies are tailor-made to exploit the attention showered on outperformers. To illustrate why, consider an allocator who filters their choice set by screening for strong active returns. Whether or not the concentrated managers deliver superior skill, the allocator is likely to find concentrated strategies overrepresented in the resulting sample, especially at the top end of the range. That’s because poorer diversification and higher active risk induce greater dispersion in concentrated managers’ performance. Consistent with that explanation, we find empirically that concentrated managers are overrepresented in both tails of the active return distribution—the worst, as well as the best.14
This problem is pernicious. Markets are noisy, and there are enough strategies in the marketplace that a decent number will throw off eye-catching track records simply due to luck. The hunger to find winners and the attendant willingness to believe ex post stories that attribute outlying outperformance to skill generates interest in those managers and their investing approaches for unsound reasons. As a group, concentrated strategies are built to appeal to this bias.
Performance Chasing
Performance chasing is another pervasive bias that plays into concentration and its underdiversified implementation. In addition to behavioral roots, the staff at many institutions feel powerful incentive to recommend investing styles and strategies that have been performing well; they see significant career risk in making idiosyncratic or contrarian calls that don’t work out.15 During the years in which concentration grew in popularity, there is little doubt that performance chasing helps to explain many an implementation through allocations to growthy, tech oriented portfolios in recent years.
Moreover, managers cater to investors’ misguided backward-looking thematic interests—closet indexing is hardly the only manifestation of asset gathering incentives gone awry. In the data-rich ETF space, academic research has documented that specialized (and relatively high-cost) ETFs, “tend to hold attention-grabbing and overvalued stocks and therefore underperform significantly …”16
Concentrated thematic investments in smaller, illiquid stocks exacerbate risks of chasing returns. As strong performance draws investor attention, new inflows may inflate prices, further boosting performance and drawing additional assets. This feedback loop poses risk to later investors, who are left holding the bag when the flow driven price momentum abates and expectations reset.17
Conclusion
A central lesson of behavioral finance is that investors should be ever watchful of behavioral biases and incentives that distort their decision making. Concentrated equity makes for an especially powerful example, because this investing approach happens to be so well-suited to exploit those vulnerabilities. Preference for right skewness, asymmetric focus on winners, and performance chasing help to explain concentration’s rise to popularity over the past decade and have influenced how it has been implemented. But we see these dangerous influences at work in many investing contexts. Stay vigilant.
References
Barberis, Nicholas and Ming Huang, “Stocks as Lotteries: The Implications for Probability Weighting for Security Prices,” American Economic Review 98, no. 5 (2008) 2066-2100.
Ben-David, Itzhak, Francesco Franzioni, Byungwook Kim, and Rabih Moussawi, Competition for Attention in the ETF Space, Working Paper, October 2022.
Brunnermeier, Markus K., Christian Gollier, and Jonathan A. Parker, “Optimal Beliefs, Asset Prices, and the Preference for Skewed Returns,” AEA Papers and Proceedings 97, no. 2 (May 2007) 159-165
Cohen, Randy, Christopher Polk, and Bernhard Silli, “Best Ideas,” Working Paper, March 2009. A later version is Anton, Miguel, Randy Cohen, and Christopher Polk, “Best Ideas,” Working Paper, April 2021.
Conine, Jr., Thomas E. and Maurry J Tamarkin, “On Diversification Given Asymmetry in Returns,” The Journal of Finance 36, no. 5 (December 1981) 1143-1155.
Cremers, Martijn and Antti Petajisto, “How Active is Your Fund Manager? A New Measure that Predicts Performance.” Review of Financial Studies 22, no. 9, (September 2009) 2239-3365.
Goyal, Amit and Sunil Wahal, “The Selection and Termination of Investment Management Firms by Plan Sponsors,” The Journal of Finance 63, no. 4 (August 2008) 1805-1847.
Heaton, J. B., N. G. Polson, and J. H. Witte, Why Indexing Works, Working Paper, May 2017.
Hendrik Bessembinder, “Do Stocks Outperform Treasury Bills?,” Journal of Financial Economics 129, no. 3 (September 2018) 440-457.
Homer, The Odyssey, 3rd century BCE
Malcolm Baker, Investor Sentiment for Value and Growth, Acadian, December 2024.
Mitton, Todd and Vorkink, Keith, Equilibrium Underdiversification and the Preference for Skewness, Working Paper, February 2005.
Ramachandran, Anshuman and Seth Weingram, Concentrated Equity: Practice Versus Premise, Acadian, October 2024.
Thirukkonda, Ram and Seth Weingram, Choosing to Lose: Country Misallocation in Discretionary EM Investing, Acadian, April 2025.
Van der Beck, Philippe, Jean-Philippe Bouchaud, and Dario Villamaina, Ponzi Funds, May 2024.